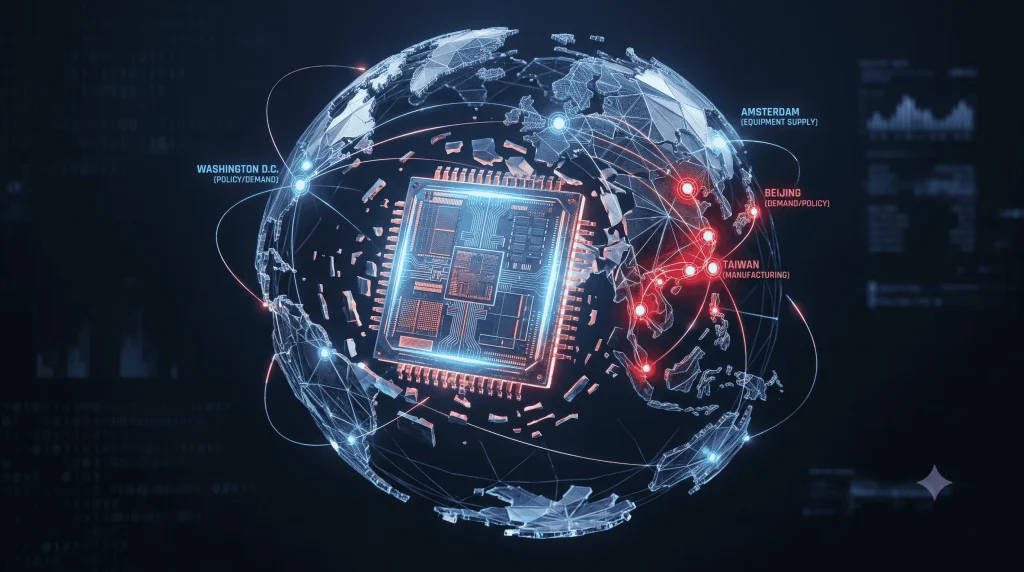

The global semiconductor industry in 2026 has transitioned irrevocably from an era of frictionless globalization to an epoch defined by geoeconomics, statecraft, and acute supply chain warfare. The central thesis of the modern technological arms race is no longer exclusively about which entity can pattern the smallest transistor, but rather who commands the interconnected chokepoints spanning the entire value chain. From upstream raw materials to midstream manufacturing equipment and advanced packaging, nations are weaponizing monopolies to secure economic and national security. The resulting “Chokepoint Economy” has fragmented the global technology stack, forcing a paradigm shift from efficiency-driven, just-in-time logistics to resilient, just-in-case industrial policies.
This comprehensive report provides an exhaustive examination of the semiconductor supply chain landscape in late 2026. It analyzes the weaponization of critical minerals, the extreme dependencies within advanced manufacturing equipment and packaging substrates, the technological breakthroughs designed to bypass physical computing limits, and the state-capitalist counter-mobilizations attempting to redraw the global economic order.
The Upstream Chokepoints: Weaponization of Critical Minerals
The physical foundations of advanced microelectronics depend on a fragile supply of refined specialty minerals. In November 2025, the U.S. Geological Survey released an updated list of 60 Critical Minerals, immediately followed by a sweeping Executive Order stressing the necessity of a multi-domain view of supply chain risk. This order highlighted that securing the supply chain requires defending against physical, cyber, and economic subversion, particularly as financial risks mount; the industry saw a 63% year-over-year increase in bankruptcies, with approximately 400 U.S. bankruptcies recorded by late 2026. The vulnerability is acute: the United States maintains a 100% net-import reliance on eleven critical minerals, including gallium, graphite, indium, and tantalum, with the People’s Republic of China (PRC) acting as the leading source for over half of these dependencies.
China’s Export Control Architecture and Predatory Pricing
Between 2023 and 2026, Beijing orchestrated a series of targeted export controls on foundational materials, alongside key downstream components such as permanent magnets and semiconductor wafers. Gallium and germanium are indispensable for high-frequency radio frequency (RF) chips, power electronics, and military radar photonics. China’s monopoly is stark: it produces over 80% of the world’s refined gallium and roughly 60% of refined germanium.
In April 2025, China drastically squeezed global exports of heavy rare earths and permanent magnets, catching Western governments largely unprepared and inflicting immediate supply chain distress. Subsequently, Beijing announced a sweeping expansion of its export control regime scheduled for October 2025. This expansion pivoted from merely regulating raw materials to controlling the entire supply chain, including processing equipment, technology transfers, and extraterritorial clauses designed to restrict foreign-made goods containing Chinese-origin inputs (even at trace levels of 0.1% by value).
Following the October 2025 Busan summit between U.S. and Chinese leadership, Beijing agreed to a temporary détente, suspending the implementation of the expanded October 9 controls until November 2026 to “study and refine” them. However, the underlying strategic vulnerability remains unmitigated. The suspension acts as a calculated geopolitical maneuver. By maintaining the threat of a complete embargo while keeping current export quotas artificially low, China effectively stifles Western capital investment in alternative ex-China refining capacity. Private markets struggle to underwrite billion-dollar heavy rare earth refining facilities when Beijing can selectively flood the market to crash prices—a tactic formally identified by U.S. policymakers as state-sponsored predatory pricing.
Simultaneously, China has weaponized its 800-item dual-use list to execute targeted geopolitical retaliation. Throughout 2026, China reduced exports of gallium and several rare earths to Japan to near zero, punishing Tokyo for its geopolitical alignments. In July 2026, Beijing added German defense contractor Rheinmetall and 13 other European entities, including a Dutch shipbuilding company, to its export control list, actively undermining allied rearmament efforts.
The Dual-Market Reality and Price Divergence
The weaponization of export licenses has fractured the global commodities market, creating a structural dual-market reality characterized by immense price divergences between Chinese domestic markets and the rest of the world. Because China’s Ministry of Commerce (MOFCOM) issues general export licenses far below required volumes, Western manufacturers are forced to pay astronomical premiums for the limited material that escapes the mainland.
This dynamic is most visible in heavy rare earths like dysprosium (essential for high-temperature stability in NdFeB magnets, EV motors, and advanced electronics) and terbium (vital for high-performance displays and clean energy technologies). The market is no longer governed by conventional supply and demand, but by geopolitics and export permission.
| Strategic Material | Primary Application | Domestic China Price (USD/kg) | Ex-China / North America Trade Price (USD/kg) | Price Premium |
|---|---|---|---|---|
| Dysprosium Oxide | Magnet HREE, EVs, Defense | $211.50 – $217.50 | ~$3,250.00 | ~1,400% |
| Terbium Oxide | Magnet HREE, Semiconductors | $987.75 – $996.75 | ~$7,500.00 | ~650% |
| NdPr Oxide | Magnet LREE, Turbines | $108.62 – $111.62 | ~$140.00 | ~25% |
| Yttrium Oxide | Strategic HREE, Coatings | $8.70 – $9.30 | Unavailable / Illiquid | N/A |
Data reflecting market conditions as of late 2026, demonstrating the extreme premium applied to materials requiring export permission.
The extraordinary premiums for dysprosium and terbium demonstrate the severe economic friction introduced by the chokepoint economy. This pricing asymmetry provides Chinese downstream manufacturers of electric vehicles, wind turbines, and electronics with a massive structural cost advantage, accelerating China’s strategy to move up the value chain from raw material supplier to dominant downstream manufacturer. A complete execution of the suspended rare earth controls could inflict up to $6.5 trillion in annual economic damage to OECD economies, underscoring the severity of the threat.
Beyond rare earths, broader mineral markets have experienced immense volatility. Driven by tight supply conditions and robust demand from the aerospace, defense, and high-tech sectors, prices for strategic minor minerals have skyrocketed. By 2026, hafnium crossed the $10,000/kg threshold due to inelastic supply and surging demand in superalloys and nuclear control rods, while lutetium—driven by next-generation medical applications—climbed from $2.2 million to $3.45 million per tonne. Germanium targets $7,000/kg and gallium approaches $2,000/kg as non-Chinese supply chains fail to scale rapidly enough to meet the deficit.
Geographic Fragility: The Spruce Pine Quartz Crisis
While geopolitical monopolies dominate the strategic discourse, the 2026 semiconductor landscape has also been profoundly shaped by geographic and environmental vulnerabilities. The global production of microchips relies entirely on the Czochralski process to pull monocrystalline silicon ingots. This process requires crucibles that can withstand molten silicon without introducing chemical impurities—a requirement satisfied exclusively by ultra-high-purity quartz.
Between 70% and 90% of the world’s natural high-purity quartz originates from a single geological anomaly: the pegmatite mines in Spruce Pine, North Carolina, operated by Sibelco and The Quartz Corp. The systemic fragility of this node was violently exposed when Hurricane Helene caused catastrophic flooding and infrastructure damage to the Spruce Pine region, forcing immediate operational shutdowns.
The disruption highlighted a critical flaw in semiconductor supply chain resilience. While synthetic quartz exists, the production process is prohibitively expensive, and current global capacity is vastly insufficient to replace Spruce Pine’s output. Furthermore, quartz crucibles degrade and introduce deformities after three to twelve uses, meaning the foundry ecosystem operates on a continuous, just-in-time replenishment cycle, typically maintaining only 30 to 60 days of inventory. The environmental shock to Spruce Pine caused immediate price surges and forced the industry to reckon with the reality that a trillion-dollar digital economy hinges on a single rural mining district vulnerable to climate-induced disruptions.
Midstream Bottlenecks: Lithography, Packaging, and Substrates
As the physical limits of Moore’s Law constrain the miniaturization of transistors, the competitive battleground has shifted. Control over the semiconductor industry is increasingly dictated by oligopolies in photolithography tooling, advanced packaging capacity, and specialized substrate materials.
The High-NA EUV Monopoly
Front-end chip fabrication at advanced nodes (sub-2nm) is entirely dependent on extreme ultraviolet (EUV) lithography. Netherlands-based ASML maintains a 100% global monopoly on commercial EUV systems, effectively serving as the ultimate gatekeeper for leading-edge logic and memory production. The broader semiconductor manufacturing equipment (SME) market is equally consolidated, with ASML, Applied Materials, Lam Research, Tokyo Electron, and KLA Corporation controlling over 70% of the global market, enabling extraterritorial export controls that block rival foundries from acquiring metrology and deposition systems.
In 2025 and 2026, the industry began its transition to High-Numerical Aperture (High-NA) EUV lithography (the ASML EXE platform). By increasing the numerical aperture from 0.33 to 0.55, High-NA EUV allows light from a wider angular range to image structures as small as 8 nanometers, paving the way for geometric scaling into the next decade.
This transition, however, exacerbates supply chain concentration. High-NA EUV relies on projection optics manufactured exclusively by Germany’s Carl Zeiss SMT. Because glass absorbs EUV light (13.5 nm wavelength), the optical path requires an ultra-high vacuum and relies entirely on highly engineered, multi-layered reflective mirrors containing over a hundred layers. The mirrors for the 0.55 NA systems are twice the size of standard EUV mirrors, weighing roughly 150 tons collectively, and must be polished to atomic precision; to measure these optics, Zeiss constructed a five-by-ten-meter vacuum chamber capable of sub-nanometer accuracy.
Furthermore, High-NA systems require an anamorphic lens design, which shrinks the reticle exposure field by half to 26 mm × 16.5 mm. This necessitates highly complex “stitching” software to seamlessly combine adjacent exposure fields on the wafer. To fully leverage the economics of High-NA EUV and eliminate the throughput penalty of half-field stitching, ASML and TSMC announced a joint initiative in September 2026 to transition the industry from traditional 6-inch photomasks to large-format 12-inch photomasks. This pilot line is targeted for 2031, with advanced node production slated for 2033, underscoring the massive capital and temporal investments required to advance lithography.
Advanced Packaging Constraints: The CoWoS Squeeze
While lithography dictates transistor density, advanced packaging has emerged as the primary structural bottleneck constraining the artificial intelligence revolution. High-performance AI accelerators, such as NVIDIA’s Blackwell GPUs, require massive memory bandwidth achieved by stacking High Bandwidth Memory (HBM) alongside the logic die. This heterogeneous integration is predominantly executed using TSMC’s Chip-on-Wafer-on-Substrate (CoWoS) technology.
Throughout 2024 and 2025, AI chip demand vastly exceeded CoWoS capacity, creating a persistent supply shortfall that throttled global AI infrastructure deployments. By mid-2026, TSMC’s aggressive capital expenditure—converting logic cleanrooms in Fab 12, 14, 15, and 18, and expanding dedicated advanced packaging facilities in Miaoli and Chiayi—pushed CoWoS capacity to approximately 120,000 to 140,000 wafer-starts per month (wpm). Supplemented by capacity from Outsourced Semiconductor Assembly and Test (OSAT) partners like ASE, SPIL, and Powertech, the global CoWoS-equivalent capacity is projected to narrow the supply-demand gap from a 20% deficit down to 10% by the end of 2026.
| Timeline | TSMC CoWoS Capacity (wpm) | OSAT Partner Capacity (wpm) | Total Industry Capacity (wpm) |
|---|---|---|---|
| End of 2024 | ~50,000 | ~5,000 | ~55,000 |
| Mid-2025 | ~80,000 | ~15,000 | ~95,000 |
| End of 2025 | ~100,000 | ~25,000 | ~125,000 |
| Mid-2026 | ~120,000 – 140,000 | ~50,000 – 60,000 | ~170,000 – 200,000 |
| End of 2026 (Est.) | ~150,000 – 160,000 | ~60,000 – 70,000 | ~210,000 – 230,000 |
Global advanced packaging capacity growth for 2.5D interposer technology, illustrating the massive industry ramp-up to meet AI demands.
Simultaneously, the architecture of the package itself is undergoing a forced evolution. Traditional CoWoS-S relies on a monolithic silicon interposer to connect the logic and HBM. As package sizes scale beyond 3.3 times the reticle limit (approximately 2,700 mm²) to accommodate more HBM stacks, manufacturing massive defect-free silicon interposers reaches physical and economic limits. These massive 3,300 mm² interposers dissipate over 2.6 kW of thermal design power (TDP), forcing TSMC to develop direct-to-silicon liquid cooling that achieves a thermal resistance of 0.055 °C/W at 40 ml/s coolant flow, vastly outperforming traditional lidded air cooling.
To bypass the size constraints of full silicon interposers, TSMC is shifting high-volume AI production to CoWoS-L, with NVIDIA securing over 70% of TSMC’s CoWoS-L capacity for 2025 and 2026. CoWoS-L utilizes a reconstituted interposer composed of an organic redistribution layer (RDL) embedded with localized silicon interconnects (LSIs). This transition preserves the ultra-high-density routing of through-silicon vias (TSVs) exactly where they are needed while reducing cost. Intel has positioned its EMIB-T technology as a competitor, but TSMC’s yield advantages currently secure CoWoS-L as the mainstream solution through 2028.
Looking toward the 2028 horizon, the industry is preparing for CoPoS—a panel-level organic substrate technology. By fabricating substrates on 510mm × 515mm panels rather than 300mm circular wafers, CoPoS provides roughly five times the usable area, enabling massive scaling of chiplet architectures while lowering the cost per unit area by 40%. However, the transition to organic packaging directly collides with another severe supply chain chokepoint: the ABF substrate monopoly.
The ABF Substrate Crisis
Advanced 2.5D and 3D packages are fundamentally reliant on Ajinomoto Build-up Film (ABF) substrates, which provide the intricate routing and thermal stability necessary to connect high-density interposers to the motherboard. Developed originally in the 1990s from amino acid chemistry, ABF has become the ubiquitous dielectric insulation material for virtually all high-performance CPUs, GPUs, and AI accelerators.
The supply chain for ABF is dangerously consolidated. Japan’s Ajinomoto Group controls approximately 95% of the global market for the film. As hyperscale data centers expand, the material requirements have compounded exponentially. While traditional PC processors require 4 to 6 layer ABF substrates, modern AI accelerators demand 8 to 16 layers, consuming up to ten times the volume of ABF film per chip. Due to this constrained supply, average selling prices for ABF substrates climbed from $65 in 2024 to $82 in 2025.
The fragility of this node was weaponized in early August 2026, when Ajinomoto notified mainland Chinese customers of a 30% reduction in ABF film supply. The move sent shockwaves through the Chinese domestic semiconductor ecosystem, which maintains a domestic ABF substitution rate of less than 5%. This targeted supply restriction functions as a potent complement to U.S. export controls: while the United States restricts the export of advanced logic and EDA software, the restriction of Japanese ABF film physically prevents Chinese foundries and OSATs from packaging whatever high-performance silicon they manage to fabricate, effectively neutralizing their domestic AI chip designs (such as Huawei Ascend).
Globally, Ajinomoto’s capacity (approximately 2 million square meters monthly) is running at absolute maximum utilization. With significant new capacity additions delayed until 2028, the global supply-demand gap for ABF substrates is projected to widen alarmingly:
| Timeline | Estimated ABF Supply-Demand Gap | Market Driver / Catalyst |
|---|---|---|
| H2 2026 | ~10% | Ajinomoto cuts mainland China supply by 30%. |
| 2027 | ~21% | AI accelerator volumes surge; existing capacity maxed. |
| 2028 | ~42% | Wait for new Ajinomoto capacity to come online. |
| 2032 | TBD | Ajinomoto third plant projected to begin production. |
Data modeling the ABF Substrate structural deficit.
To secure access, fabless chipmakers are taking extraordinary measures. AMD, for instance, executed a $400 million co-investment venture with Siliconware Precision Industries simply to secure 30% of a new Taiwanese facility’s output. These forward-buy agreements squeeze mid-tier vendors out of the market entirely, cementing a capacity oligopoly that will persist as long as hyperscale operators continue deploying millions of AI accelerators annually.
Technological Breakthroughs: Bypassing Physical Limits
As the semiconductor industry navigates these geopolitical and material bottlenecks, it is simultaneously forced to re-engineer fundamental chip architectures to overcome the physical limits of power consumption and thermal dissipation. In 2026, two transformative technologies entered the mainstream commercialization phase: Silicon Photonics and Ultra-Wide Bandgap (UWBG) materials.
Silicon Photonics and Co-Packaged Optics (CPO)
The AI infrastructure boom has driven electrical interconnects to their absolute physical boundaries. Transmitting high-speed electrical signals across copper traces results in severe signal degradation, latency, and extreme power consumption, ultimately capping switch bandwidths.
To shatter this “power wall,” the industry has rapidly pivoted to Co-Packaged Optics (CPO). CPO utilizes silicon photonics technology to integrate the optical engine directly onto the same package substrate as the switch ASIC or GPU, effectively running an optical fiber highway straight into the heart of the chip. By replacing copper wiring with optical fiber at the chip level, CPO minimizes the electrical trace distance, yielding 30% to 50% reductions in power consumption while supporting bandwidth leaps to 1.6T, 3.2T, and beyond.
In the second half of 2026, CPO officially transitioned from validation to volume mass production. TSMC’s Compact Universal Photonic Engine (COUPE) platform, which integrates micro ring modulators (MRMs) on a 3-nm process, serves as the foundry backbone for this transition. Industry leaders Broadcom (with its Bailly CPO switches) and NVIDIA (incorporating CPO into its Spectrum-X switches, GB300 chips, and signaling CPO for its upcoming Rubin architecture to bypass NVLink limits) are driving adoption across hyperscale AI fabrics.
The strategic implication of CPO is immense. It forces a convergence of the semiconductor and telecommunications supply chains. Vertical integration has become mandatory. Entities that can control in-house indium phosphide (InP) epitaxy for lasers (such as LandMark, which saw its 2025 EPS reach NT$4.66 due to silicon photonics demand), silicon photonics design, and advanced 3D packaging (like Accton and GCS Holdings) will dominate the next decade of data center networking.
Ultra-Wide Bandgap Semiconductors: The Gallium Oxide Era
While silicon photonics addresses data transmission, power conversion and high-voltage regulation for electric vehicles and smart grids are demanding entirely new material classes. First-generation wide-bandgap materials like Silicon Carbide (SiC) and Gallium Nitride (GaN) are approaching their theoretical limits. The focus has rapidly shifted to Ultra-Wide Bandgap (UWBG) semiconductors, with Beta-Gallium Oxide (β-Ga2O3) emerging as the premier candidate for grid-scale power electronics and deep-UV photonics.
Beta-Gallium Oxide possesses a colossal bandgap of 4.9 eV and a theoretical breakdown electric field of 8 MV/cm. Its most critical metric, Baliga’s Figure of Merit (BFOM)—which measures the trade-off between blocking voltage and conduction loss—is estimated at 3,300 to 4,000 times that of traditional silicon, and roughly 3 to 10 times higher than SiC and GaN. Crucially, unlike SiC, which requires slow and expensive physical vapor transport growth at temperatures exceeding 2,000°C using complex sublimation reactors, β-Ga2O3 melts congruently at 1,820°C. This allows it to be grown from the melt using standard Czochralski methods borrowed from the silicon industry, promising significantly lower substrate costs and rapid scaling to 6-inch and 8-inch wafers.
However, the material suffers from two profound engineering barriers. First, its flat valence band structure currently prohibits practical p-type doping, forcing designers to rely exclusively on unipolar devices or deep-acceptor compensation. Second, β-Ga2O3 exhibits abysmal anisotropic thermal conductivity (roughly 10-27 W/m·K, or 0.27 W/cm·K, significantly lower than SiC or GaN).
To prevent these high-power devices from overheating, research in 2025 and 2026 has focused aggressively on heterogeneous integration. By utilizing metal-organic chemical vapor deposition (MOCVD) to grow thin films of β-Ga2O3 on single-crystal diamond substrates (which possess a thermal conductivity of ~10 W/cm·K, nearly 37 times higher than gallium oxide), engineers have successfully mitigated the thermal penalty while preserving the ultra-high voltage blocking capabilities. The patent landscape in 2026 reveals a surge in intellectual property filings from institutions like Southeast University, which patented a heterogeneous complementary cascade combining gallium oxide depletion-mode transistors with diamond enhancement-mode transistors. Additionally, Xidian University patented a low-ohmic-contact fabrication method using a heavily silicon-doped spin-on-glass (SOG) interlayer, solving critical contact resistance issues. Beyond power, the UWBG landscape is expanding into deep-UV sterilization (UVC 200–280 nm) for water and air disinfection, capitalizing on the unique photonic properties of these materials.
State-Capitalist Counter-Mobilizations
Recognizing that market forces alone cannot untangle the embedded monopolies of the PRC, Western and allied nations have rapidly instituted state-capitalist frameworks. These policies aim to artificially stimulate alternative supply chains, subsidize deep-tech manufacturing, and weaponize export controls to safeguard economic security.
The United States: Pax Silica, Project Vault, and Export Controls
In December 2025, the U.S. Department of State launched Pax Silica, a flagship geoeconomic coalition headed by Under Secretary of State Jacob Helberg, designed to secure the global technology stack from upstream mineral extraction through midstream processing to downstream AI infrastructure. Pax Silica operates on the premise of “coalition logic,” aiming to eliminate critical vulnerabilities by networking the complementary capabilities of allied nations. The coalition, explicitly excluding China, quickly expanded from 11 founding signatories to 24 by mid-2026, establishing a parallel governance structure that directly competes with China’s World Artificial Intelligence Cooperation Organization (WAICO).
Pax Silica represents the third track of a broader U.S. critical minerals diplomacy strategy. The first track focuses on ‘America First’ domestic state intervention, such as the Department of Energy’s $2.3 billion loan for Lithium Americas’ Thacker Pass project. The second relies on bilateral public-finance pacts overseas. The third, Pax Silica, ties it all together into a coordinated ecosystem spanning energy, processing, logistics, and advanced manufacturing across jurisdictions like Australia, Japan, and the UK.
Domestically, the U.S. government took unprecedented steps in February 2026 with the announcement of Project Vault. Supported by a historic $10 billion loan from the Export-Import Bank of the United States (EXIM) and complemented by nearly $2 billion in private capital, Project Vault established a civilian strategic reserve for critical minerals run by an independent private entity, VaultCo. The initiative aims to shield U.S. manufacturers from supply shocks orchestrated by Beijing and provide price floors to guarantee off-take for nascent non-Chinese mining ventures.
However, Project Vault contains a structural vulnerability. While it provides immense liquidity to stockpile raw materials, the program is demand-driven by downstream manufacturers and lacks explicit sourcing mandates or processing restrictions. Because the U.S. suffers from a near-total deficit in heavy rare earth separation and midstream chemical refining, there is little to prevent manufacturers from drawing raw materials from the Vault, only to export them back to China for processing. This exposes a critical reality: controlling the mine is insufficient if the geopolitical adversary controls the refinery.
Simultaneously, an intense debate has emerged within Washington regarding the efficacy of unilateral export controls. The U.S. strategy of choking China’s access to advanced AI chips (GPUs) and lithography tools has proven a double-edged sword. “Chip Hawks” argue that draconian controls are necessary to starve the Chinese military-civil fusion apparatus of compute power. Conversely, “Diffusers” argue that overly stringent controls are counterproductive; they sacrifice U.S. market share, alienate allied equipment providers in Europe and Japan, and ultimately force China to accelerate its indigenous capabilities.
This forced indigenization is evident in China’s growing dominance in legacy chip manufacturing. Barred from the leading edge, Chinese capital has flooded into mature nodes (28nm and above). China’s production share of legacy semiconductors is projected to grow from 30% to over 45% by 2030, presenting a severe latent threat to the global automotive and industrial supply chains. By capturing the legacy chip market, China gains immense leverage over Western automotive OEMs, who rely entirely on these older nodes for power management ICs, vehicle control units, and smart cabin architectures.
India’s Quest for Strategic Autonomy: NCMM and Dholera SIR
Faced with extreme vulnerabilities—importing nearly 90% of its rare-earth requirements from China and possessing stockpiles that would last only two to three weeks in an embargo—India has emerged in 2025 and 2026 as a highly aggressive player attempting to forge strategic autonomy.
The foundation of this push is the National Critical Minerals Mission (NCMM), launched in early 2025 with an expanding financial outlay exceeding ₹340 billion (~US$3.57 billion) over seven years. The NCMM fundamentally restructured India’s approach to the upstream supply chain. Through sweeping amendments to the Mines and Minerals (Development and Regulation) Act (MMDR), the Indian government broke historical state monopolies held by entities like India Rare Earths Ltd (IREL), introduced single-window clearances via the PARIVESH portal, and executed aggressive auctioning.
By mid-2026, 56 critical and strategic mineral blocks had been successfully auctioned out of 88 offered, covering graphite, REEs, vanadium, and titanium across states like Gujarat, Uttarakhand, and Telangana. To bypass long lead times in domestic exploration, the state-owned joint venture Khanij Bidesh India Limited (KABIL) was mandated to acquire overseas assets, successfully securing five brine-type lithium blocks in Argentina and initiating due diligence on critical mineral assets in Australia. Furthermore, the NCMM implemented a ₹1,500 crore incentive scheme to boost recycling capacity to 270 kilotonnes annually, targeting e-waste and lithium-ion batteries.
| NCMM Strategic Target (2024-2031) | Objective / Metric |
|---|---|
| Domestic Exploration Projects | 1,200 projects executed by GSI |
| Foreign Asset Acquisition | 50 foreign critical mineral mines (PSUs and Pvt.) |
| Patents in Value Chain | 1,000 patents filed and supported |
| Recycled Materials | 400 kilotonnes of recycled critical minerals |
| Centres of Excellence (CoE) | 7 CoEs established (e.g., IIT Bombay) for R&D |
Key metrics and targets outlined under India’s National Critical Mineral Mission.
Recognizing that upstream security must be paired with downstream consumption, the Indian government allocated ₹40,000 crore in the Union Budget 2026 specifically to support the semiconductor manufacturing ecosystem. The centerpiece of this downstream strategy is the Dholera Special Investment Region (SIR), India’s first greenfield smart city tailored expressly for high-tech manufacturing.
Covering 920 sq. km., Dholera benefits from a “plug-and-play” infrastructure model. Essential utilities were constructed in the 22.5 sq. km Activation Area prior to industrial occupation. This infrastructure includes uninterrupted dual-source power grids scalable to 2000 MVA, a 50 MLD scalable water treatment facility feeding from the Narmada Canal (designed to meet a total demand of 1,043 MLD), a 20 MLD common effluent treatment plant (CETP), and extensive underground ICT corridors. Additionally, renewable energy requirements are supported by the massive 5000MW Dholera Solar Park.
This derisked environment secured the ₹91,000 crore investment by Tata Electronics to build India’s first commercial semiconductor fabrication plant, targeting 28nm to 110nm legacy nodes. By mid-2026, construction at the Tata fab was advancing rapidly, supported by an ecosystem that includes a 363-acre vendor park for 450 chip suppliers and a strategic partnership with ASML. The impending operational launch of the Dholera International Airport in late 2026 and the Ahmedabad-Dholera Expressway firmly establish India as an emergent node in the global semiconductor realignment. India further solidified its geopolitical alignment by officially signing the U.S.-led Pax Silica declaration in February 2026, embedding itself within the allied technology ecosystem and committing to joint AI and critical mineral developments.
Conclusion: Navigating the 2026 Chokepoint Economy
An analysis of the 2026 semiconductor and critical mineral landscape reveals several profound strategic implications for the global economy. The structural balkanization of technology is permanent. Initiatives like Pax Silica and China’s WAICO are not mere diplomatic forums; they represent the foundation of competing, mutually exclusive technological ecosystems. Supply chain managers must now operate on the assumption that components, raw materials, and intellectual property cannot easily cross these geopolitical boundaries.
The industry has entered an era of geoeconomic price discovery. Commodity pricing for critical elements is no longer tethered strictly to extraction costs and global demand. Because China leverages export licenses to isolate markets, dual-pricing structures will become standard. Western downstream manufacturers must factor massive “geopolitical premiums” into their cost of goods sold, while state entities will be forced to employ mechanisms like Project Vault to subsidize the difference.
Simultaneously, as transistor scaling yields diminishing returns and lithography costs spiral under High-NA EUV, value generation is migrating downstream to advanced packaging. The evolution of CoWoS and the integration of Co-Packaged Optics dictate that the performance of a system is now fundamentally constrained by substrate availability (ABF) and interconnect density, rather than pure logic node capability.
Ultimately, the hyper-concentration of capabilities remains the industry’s greatest unmitigated risk. Whether it is a 95% reliance on a Japanese chemical company for packaging substrates, a 100% reliance on a Dutch-German duopoly for extreme ultraviolet lithography, or an absolute dependency on a single Appalachian town for high-purity quartz, the system is brittle. Geopolitics is a primary vector for disruption, but as extreme weather events like Hurricane Helene demonstrate, geographic concentration leaves the global digital economy intensely vulnerable to acute environmental shocks. Securing the semiconductor supply chain in this new era requires an unprecedented synchronization of industrial capability, diplomatic coalition-building, and massive state capital deployment.
About The Author